




Alphabet (GOOGL) Q3 earnings preview: US$200 billion AI capex test puts major uptrend at risk
Key takeaways
- Google Cloud is the key growth catalyst, but investors will watch whether rapid AI-driven revenue expansion is matched by healthy margins and cash generation.
- Capex and free cash flow are the biggest valuation risks, especially if Alphabet raises spending again without clearer evidence of improving AI returns.
- Technically, 359.44 is the key resistance, while a break below 300.44 may expose 270.70 and signal a deeper deterioration in the major uptrend.
Ahead of Wednesday’s Q3 2026 earnings, Alphabet (GOOGL) faces a critical test of whether surging demand for artificial intelligence (AI) computing can sustain its rapid Google Cloud growth while offsetting mounting concerns over infrastructure spending, free cash flow and profitability.
Alphabet is expected to release its Q3 results after the US market closes on Wednesday, 28 October 2026, with its earnings conference call scheduled for 4:30 pm Eastern Time.
Based on the street’s expectations, there is an underlying divergence: revenue is expected to increase by nearly 25% year-on-year to US$127.92B, but EPS growth is projected at just 5.6% year-on-year to US$3.02.
Highlighting the market’s focus on whether AI infrastructure costs are beginning to dilute underlying earnings growth. EPS comparisons also require care because Alphabet’s Q2 results included unusually large investment-related gains.
Following weakness in AI-linked technology stocks since the start of October, investors are increasingly questioning whether aggressive capital expenditure commitments will generate sufficient returns to justify elevated valuations.
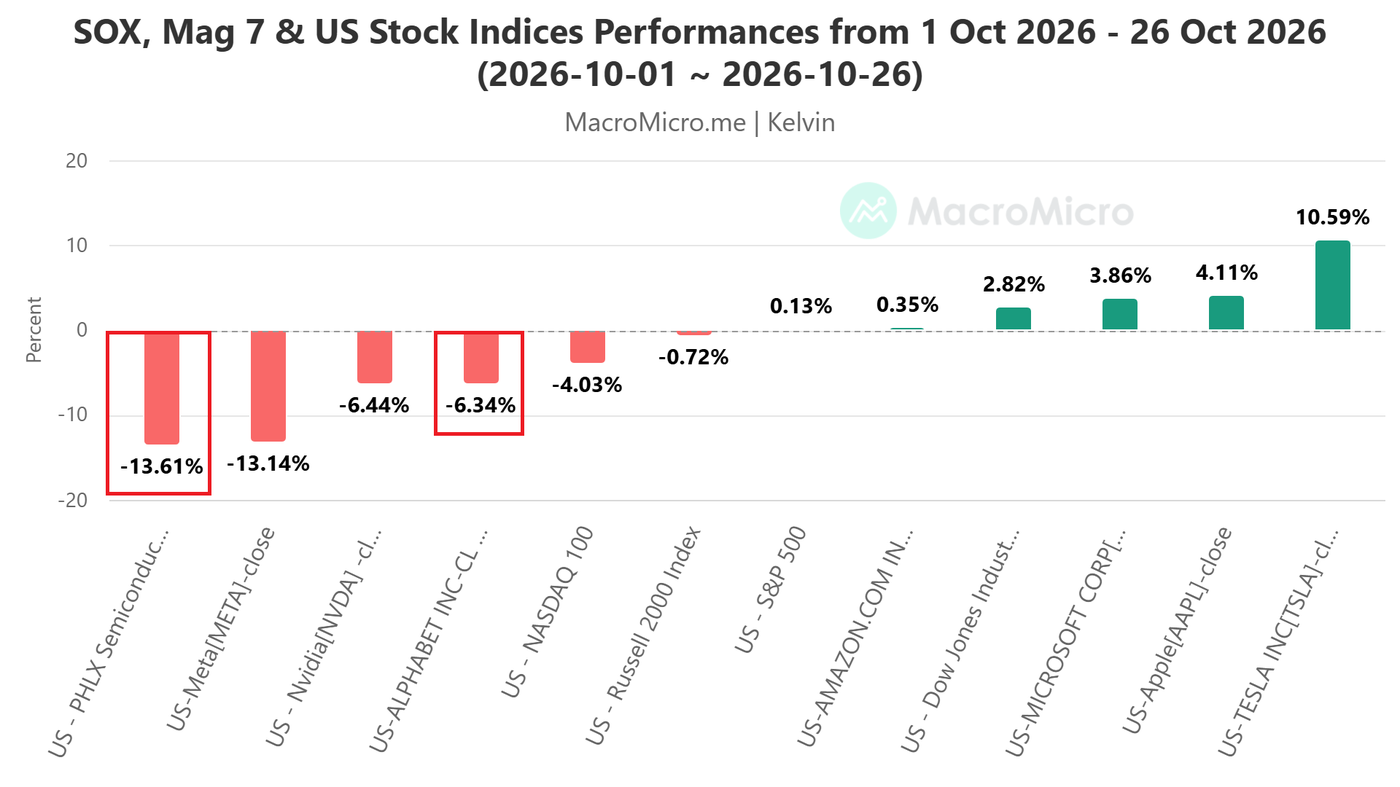
Alphabet’s shares recorded a loss of 6.34% from the start of October through 26 October 2026, reflecting broader weakness in AI-related technology stocks, with juggernaut Nvidia and the US PHLX Semiconductor Sector Index declining by 6.44% and 13.61% respectively (see Fig. 1).
Ahead of Alphabet’s Q3 earnings release, options markets are pricing an approximately ±6.0% move in Alphabet’s (GOOGL) shares as of 26 October 2026, almost on par with its 10-year average peak earnings-day movement of 6.6%, according to data from EarningsWatcher.
Against this backdrop, Alphabet’s earnings reaction is likely to hinge on six key fundamentals.
1. Google Cloud: the most important earnings growth catalyst
Google Cloud revenue surged 82% year on year to US$24.8 billion in Q2 2026, driven by enterprise AI infrastructure, enterprise AI solutions and core cloud services. Cloud growth significantly outpaced the wider group’s 24% revenue expansion. [1]
Importantly, Cloud has become Alphabet’s clearest avenue for monetising the AI infrastructure boom, benefiting from rising demand for Google Cloud Platform, Gemini-related workloads and its proprietary Tensor Processing Units (TPUs).
J.P. Morgan recently raised its Alphabet price target from US$420 to US$425, expecting Google Cloud’s Q3 revenue to approximately double from the same period a year ago.
2. Google Search advertising: can AI strengthen rather than undermine its core business?
Google Search remains Alphabet’s largest profit engine and an important source of funding for its capital-intensive AI expansion.
In Q2, Google Services revenue increased 15% year on year to US$94.5 billion, supported by 17% growth in Google Search and other advertising revenue, while YouTube advertising revenue increased 13%.
Traders will likely focus on whether AI-powered Search experiences, including AI Overviews and Gemini integration, are driving higher engagement and commercial search activity without undermining traditional advertising monetisation.
The market is particularly sensitive to whether conversational AI services divert users from conventional search queries and reduce the number of profitable advertising opportunities.
3. Capital expenditure and free cash flow: the biggest valuation risk
Alphabet raised its full-year 2026 capital expenditure guidance by US$15 billion to US$195 billion–US$205 billion following its Q2 earnings, reflecting accelerated investment in AI computing, data centres and network infrastructure.
The spending increase comes amid mounting concerns over the sustainability of the AI investment cycle. In the first six months of 2026 alone, Alphabet recorded US$80.6 billion in capital expenditure, compared with US$39.6 billion during the same period in 2025. [2]
Of particular concern, Alphabet reported negative free cash flow of approximately US$5.9 billion in Q2 despite strong revenue growth.
Traders will focus on three questions: whether 2026 spending guidance will increase again, whether management expects another substantial rise in 2027, and whether AI-generated revenue can eventually outpace growth in infrastructure costs.
4. Operating margins: Is AI growth translating into higher profitability?
Alphabet’s Q2 operating income rose 30% year on year, with its operating margin expanding by two percentage points to 34%.
However, rising depreciation, energy requirements, personnel expenses, and infrastructure costs could gradually erode operating leverage as new data-centre capacity comes online.
Investors will closely monitor Google Cloud operating profitability alongside Alphabet’s consolidated operating margin to determine whether the rapid expansion in AI-related revenue is translating into sustainable earnings growth.
A further complication is Alphabet’s investment-related gains. Q2 reported EPS of US$9.11 was significantly boosted by non-operating investment gains, while underlying EPS excluding those gains was approximately US$2.85.
5. Gemini, TPUs and enterprise AI monetisation
Beyond the headline Cloud revenue numbers, investors will assess whether Alphabet’s vertically integrated AI strategy is generating a sustainable competitive advantage.
Alphabet’s proprietary TPU infrastructure provides an alternative to Nvidia GPUs, while Gemini models and enterprise AI services offer additional monetisation opportunities across Google Cloud, Workspace and consumer products.
In Q2, Alphabet began recognising revenue from direct TPU sales, while its Cloud order backlog reportedly reached US$514 billion.
This creates an important potential growth driver; Alphabet can benefit not only from operating its own AI infrastructure but also from supplying computing capacity and specialised hardware to external customers.
6. Forward guidance and macroeconomic conditions
Alphabet reports during a period of elevated uncertainty surrounding US interest rates, inflation and the sustainability of AI infrastructure investment.
The recent weakness in technology and semiconductor stocks has been amplified by concerns over higher Treasury yields and the potential for additional Federal Reserve tightening.
This environment creates two distinct risks for Alphabet.
First, higher interest rates increase the discount rate applied to future earnings, potentially weighing on valuation multiples even if its operational performance remains strong.
Second, persistent inflation and higher energy prices could raise data-centre operating costs while dampening corporate advertising budgets and enterprise technology spending.
At the same time, a resilient US economy and sustained enterprise investment in AI could provide an offsetting tailwind for both Google Search advertising and Google Cloud.
Share-price implication: Strong fourth-quarter guidance, continued advertising resilience, and confident AI spending commentary could support a recovery in Alphabet’s shares. Conversely, weaker advertising demand, accelerating infrastructure costs, or more cautious management commentary could reinforce recent selling pressure across AI-related technology stocks.
Fundamental bottom line: what matters most for traders
Alphabet’s Q3 earnings reaction will likely hinge on four key factors: Google Cloud growth, Search advertising resilience, AI capital expenditure and operating margin performance, with forward guidance playing a decisive role in determining the stock’s post-earnings direction.
The bull case is clean earnings beat, accelerating Google Cloud revenue growth, resilient Search advertising demand and improving AI monetisation, supported by stable capital expenditure guidance and healthy operating margins.
This would reinforce Alphabet’s competitive advantage in AI infrastructure and potentially trigger further valuation expansion.
The bear case is not necessarily disappointing headline earnings, but signs that AI infrastructure spending is rising faster than revenue and profitability.
Slowing Cloud growth, weaker Search monetisation, margin compression or another substantial increase in 2027 capital expenditure expectations may trigger selling pressure, particularly amid heightened scrutiny of AI investment returns.
Let’s now focus on the medium-term outlook of Alphabet’s share price from a technical analysis perspective.
Technical analysis: Major uptrend in jeopardy
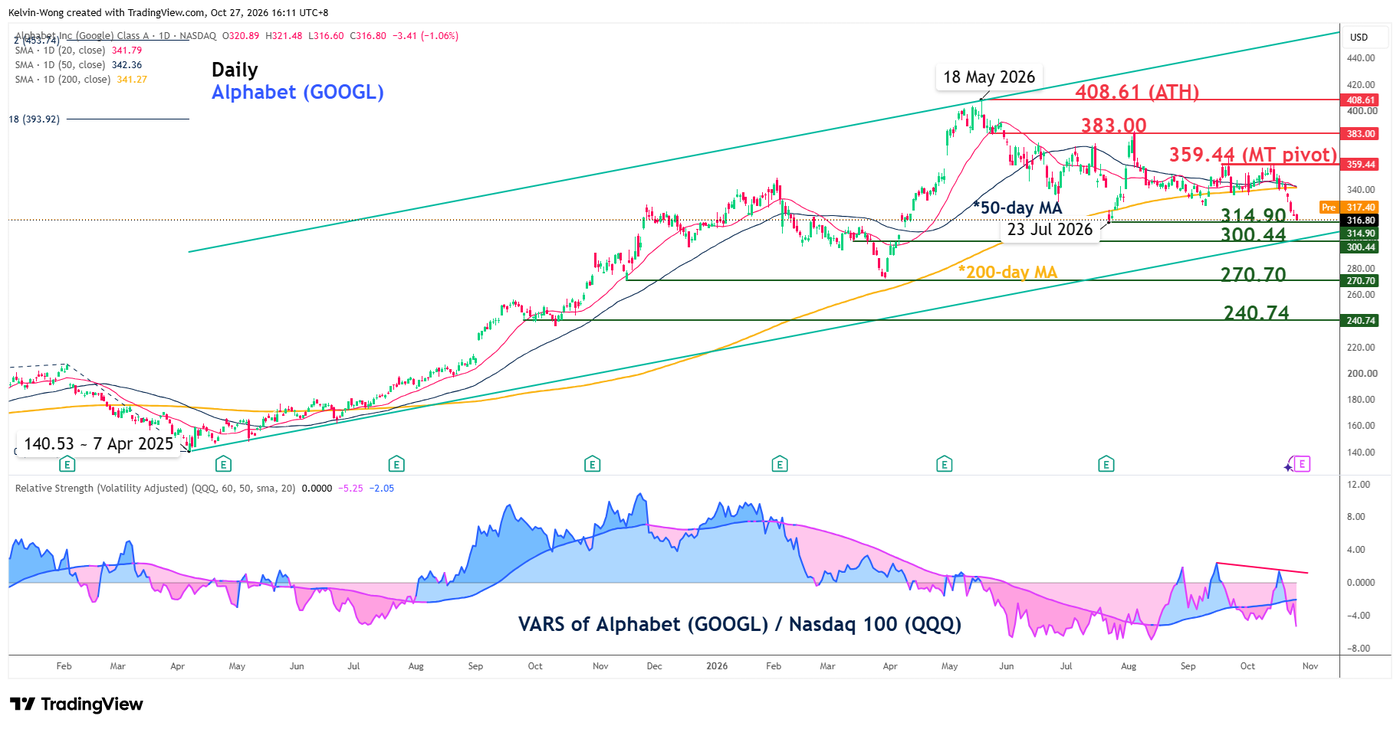
Since printing its current all-time intraday high of 408.61 on 18 May 2026, Alphabet (GOOGL) has staged a corrective decline of 22.9%, hitting a low of 314.90 on 23 July 2026.
Recent price action in GOOGL suggests that the bears are likely in control, and it faces an increasing risk of a breakdown from its current major uptrend phase, in place since the 7 April 2025 low of 140.53 (see Fig. 2).
GOOGL has staged a bearish breakdown below its 50- and 200-day moving averages.
In addition, the volatility-adjusted relative strength (VARS) of GOOGL against the Nasdaq 100 exchange-traded fund (QQQ) has trended downward since 16 October 2026, indicating further potential underperformance of GOOGL relative to the Nasdaq 100.
Watch the 359.44 key medium-term pivotal resistance to maintain the bearish bias for GOOGL; a break below 300.44 support (also the lower boundary of the major ascending channel) may trigger another potential multi-week corrective down move to expose the next medium-term support at 270.70 in the first step.
On the other hand, a clearance and a daily close above 359.44 would invalidate the bearish bias, with the next medium-term resistance at 383.00, before a potential retest of the current all-time intraday high of 408.61.
Opinions are the authors'; not necessarily that of OANDA Business Information & Services, Inc. or any of its affiliates, subsidiaries, officers or directors. The provided publication is for informational and educational purposes only.
If you would like to reproduce or redistribute any of the content found on MarketPulse, an award winning forex, commodities and global indices analysis and news site service produced by OANDA Business Information & Services, Inc., please refer to the MarketPulse Terms of Use.
Visit https://www.marketpulse.com/ to find out more about the beat of the global markets.
© 2026 OANDA Business Information & Services Inc.